Summary
In recent days, financial and social media have been buzzing with warnings of a potential “lost decade” for stocks and a looming “market reckoning” for bonds. Notably, Goldman Sachs has cautioned that the S&P 500 may experience slower growth, while prominent investor Paul Tudor Jones predicts a financial crunch tied to unsustainable government spending.
While these headlines are designed to grab attention — whether for internet clicks or television ratings — they often overlook critical underlying data. Although no one can predict the future with certainty, both perspectives reinforce our long-standing belief in the power of a diversified portfolio to navigate the unpredictable challenges ahead.
Stocks on a Road to “Nowhere”
On the equity side, there are warnings that the S&P 500 may deliver a 3% annualized total return in the next decade, translating to a 1% real return over that time. Factors such as high valuations, market concentration, possible economic contraction, corporate profitability, and interest rates are fueling the concerns. Not shared in headlines was additional commentary in the analysis that:
- Bonds are likely to outperform large cap stocks
- Non-market cap weighted investments (i.e., the non-Magnificent 7) may outperform by 2% to 8% annualized.
Both conclusions are non-trivial yet fail to grab headlines
While we agree that equity valuations, particularly for the largest U.S. companies, are high, we disagree with the notion that valuations alone will drive stocks to stagnate. Over the long term, equity markets are driven by changes in valuations, earnings growth, and dividends. As long as earnings and dividends continue to grow, that offers support for stocks to offset the impacts of elevated valuations. Current dividends for the S&P 500 are at 1.3% annualized, and earnings growth over the next decade is expected to be between 5-6% per year. Historically, U.S. companies have consistently grown earnings by 6.5% per year over the last century.
We are long standing proponents of being cognizant that the price you pay matters when it comes to owning any investable asset. Higher prices translate to lower future returns, and vice versa. Mega-cap stocks, while commanding high valuations, also deliver historically high earnings, return on equity, and revenue growth rates. While some degree of mean reversion may occur, this is far from a repeat of the 1999-2000 tech bubble, where fundamentals were entirely disconnected from stock prices. For example, the “Magnificent 7” stocks currently boast a return on equity of over 30%, while the rest of the S&P 500 sits at roughly half that figure.
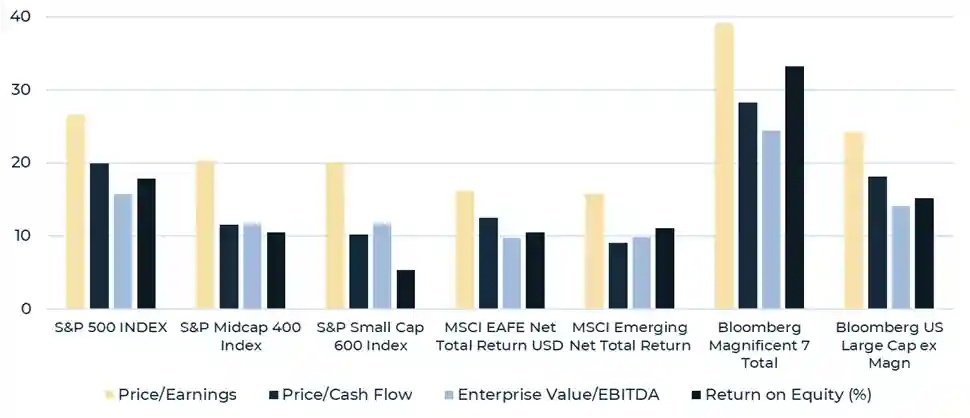
Source: Bloomberg Finance, L.P. (data as of 10/22/2024)
We utilize valuations as a guardrail to protect against potential disappointment in the future, which reinforces the importance of diversifying away from the top of the market. Including value stocks alongside growth, small-, and mid-cap stocks, as well as international investments can provide balance. As one example, small cap stocks were hit hard by rising funding costs in 2022 and continue to trade at a discount to their own history and relative to larger counterparts.
While focusing on the largest U.S. companies was a successful strategy over the past decade — and may continue to be in the near term due to the rise of artificial intelligence and its associated productivity gains — there are ample opportunities elsewhere in the market. Ignoring these opportunities in favor of a single market narrative removes valuable context about other segments of portfolios that remain undervalued. Additionally, U.S. Real GDP continues to expand at a remarkable 3% year-over-year, defying expectations of a slowdown. If this trend persists, a decade of no returns in U.S. equity markets seems unlikely.
What About Bonds?
Paul Tudor Jones takes a different stance, suggesting that bonds face a Minsky Moment of higher government spending contributing to a sudden selloff in government debt markets. Tudor Jones specifically says, “We are going to be broke really quickly unless we get serious about dealing with our spending issues.” Later in the conversation, it is shared that there are plenty of solutions, including TCJA tax cut expirations, raising payroll taxes, increasing the corporate tax rate, increasing individual tax rates, means testing on Medicare, and raising the age of Social Security, to cover just a few.
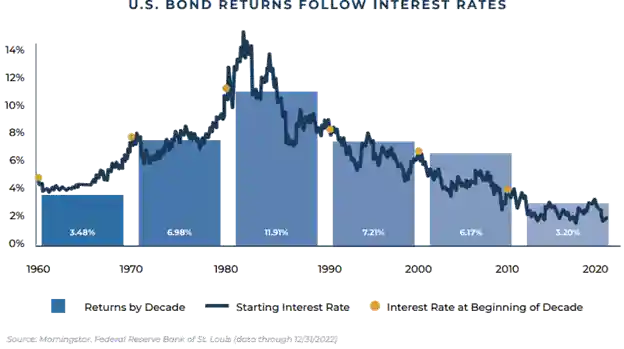
While concerns about fiscal sustainability are valid with recently large federal deficits ($1.8 trillion in fiscal 2024 or 6.4% of GDP) in a time of economic strength and growing federal debt (124% of GDP) on the U.S. balance sheet, the reality for investors is that higher yields present opportunities. As history shows, starting yields have been a strong predictor of future returns for fixed income investors, even during periods of inflation and economic fluctuation.
The U.S. remains in a privileged position with its status as the reserve currency of the world, which offers a great deal of flexibility to navigate higher levels of debt and fiscal spending. There is a potential for bond markets to force the hand of the government if yields on government debt ultimately move higher, but from the standpoint of investors, higher yields are good news, particularly for those individuals with a bias towards saving. The low to zero interest rate period from 2009-2021 meant investors began to embrace more risk within their portfolios through increased equity exposure to generate returns. We are now returning to a backdrop of balanced portfolios offering the opportunity to achieve financial goals with potentially lower imbedded risk.
Conclusion
While alarming headlines can be hard to ignore, they often fail to capture the full picture. A diversified portfolio remains one of the most effective ways to navigate uncertain markets. Whether it’s concerns about stocks facing a “lost decade” or bonds bracing for a reckoning, history shows that spreading investments across asset classes offers a more stable path forward. As always, maintaining a long-term perspective and staying focused on fundamentals will be key in helping clients achieve their financial goals, regardless of the challenges that lie ahead.
Wealthspire Advisors LLC and certain of its affiliates are separately registered investment advisers. © 2026 Wealthspire
This material should not be construed as a recommendation, offer to sell, or solicitation of an offer to buy a particular security or investment strategy. The information provided is for informational purposes only and should not be relied upon for accounting, legal, or tax advice. While the information is deemed reliable, Wealthspire cannot guarantee its accuracy, completeness, or suitability for any purpose, and makes no warranties with regard to the results to be obtained from its use.
Wealthspire and its representatives do not provide legal or tax advice, and Wealthspire does not act as law, accounting, or tax firm. Services provided by Wealthspire are not intended to replace any tax, legal or accounting advice from a tax/legal/accounting professional. The services of an appropriate professional should be sought regarding your individual situation. You should not act or refrain from acting based on this content alone without first seeking advice from your tax and/or legal advisors.
Certain employees of Wealthspire may be certified public accountants or licensed to practice law. However, these employees do not provide tax, legal, or accounting services to any of clients of Wealthspire, and clients should be mindful that no attorney/client relationship is established with any of Wealthspire's employees who are also licensed attorneys.
Please Note: Limitations. The achievement of any professional designation, certification, degree, or license, recognition by publications, media, or other organizations, membership in any professional organization, or any amount of prior experience or success, should not be construed by a client or prospective client as a guarantee that he/she will experience a certain level of results or satisfaction if Wealthspire is engaged, or continues to be engaged, to provide investment advisory services, nor should it be construed as a current or past endorsement of Wealthspire by any of its clients or a third party.
Registration of an investment advisor does not imply that Wealthspire or any of its principals or employees possess a particular level of skill or training in the investment advisory business or any other business.
Certified Financial Planner Board of Standards, Inc. (CFP Board) owns the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States, which it authorizes use of by individuals who successfully complete CFP Board's initial and ongoing certification requirements.