Investing isn’t just about picking the right mix of stocks and bonds. It’s about understanding the forces that influence markets and how your own behavior can impact outcomes. Economic trends, government policy, and even human psychology all shape the environment in which your financial plan operates. By learning how these factors interact, you can make more informed decisions and stay focused on your long-term goals.
This blog builds on concepts from our Investing 201 webinar, which explored topics beyond the basics introduced in Investing 101. If you missed the session, you can watch the full webinar on our YouTube channel here.
Understanding the Economy: The Big Picture
One way to think about the economy is like a balloon: it can only expand so much, limited by factors like population and productivity. There are only so many people available to work, and each person can only produce so much with the resources and technology at hand. When the economy is growing, the balloon inflates as businesses thrive, jobs increase, and confidence rises. Eventually, it reaches its limit and sometimes stretches too far, creating pressure that leads to a slowdown or even a recession. When the economy slows, the balloon deflates as spending pulls back and growth cools. When the economy shifts, policymakers step in to guide it using monetary and fiscal tools.
Who Helps Steer the Ship?
Governments and central banks use policy tools to guide the economy, especially during challenging times. Back to the balloon analogy: it is the job of policymakers to keep the economy from stretching too far past its capacity and to prevent contractions from being too severe.
- Monetary Policy: The Federal Reserve influences the economy by setting interest rates and controlling the money supply.
- Fiscal Policy: Government spending and tax policy also play a role in driving growth or slowing it down.
For example, during the COVID pandemic, central banks lowered rates while governments provided stimulus checks to help households and businesses weather the storm. These actions demonstrate how policy can cushion economic shocks and support recovery.
Market Cycles: The Ups and Downs Are Normal
Markets move through cycles of growth and contraction, and understanding these phases can help you stay grounded when volatility strikes. Different asset classes perform better in different environments: stocks often thrive during expansions, while bonds tend to shine during contractions. Recognizing these patterns is key to maintaining perspective and avoiding emotional decisions. The cycle includes:
- Expansion: Businesses thrive, markets rise
- Peak: Growth slows, prices may begin to peak
- Contraction (Recession): Markets decline, but this phase doesn’t last forever
- Recovery: Conditions improve and markets stabilize
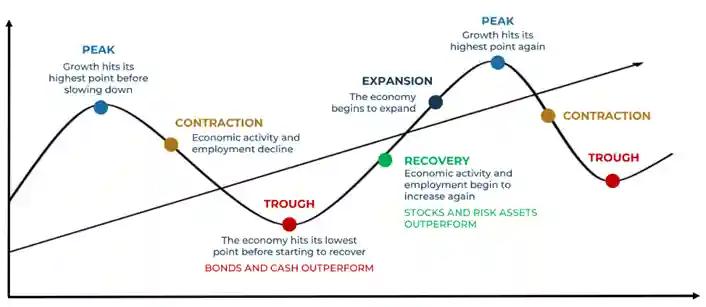
History shows that market cycles are inevitable but temporary. Over the past century, every recession has been followed by recovery and growth. If that’s true, why not sell when things look bad and buy back when things improve? The challenge is that markets move ahead of the economic cycle and often rebound before recovery is confirmed. Every recession looks obvious in hindsight, but in real time, even experts struggle to call the bottom or the top. In fact, the National Bureau of Economic Research (NBER), the official arbiter of U.S. recessions, makes its announcements only after the fact. The committee waits for revised data and clear evidence before declaring recession start and end dates, which means those calls come well after the market has already moved.
Behavioral Finance: Why Emotions Matter
Investing is as much about psychology as it is about numbers. Emotions like fear and excitement can drive investors to make poor decisions, such as buying high when optimistic or selling low when fearful. Cognitive biases like confirmation bias, mental accounting, and recency bias can cloud judgment and lead to suboptimal outcomes.
- Confirmation Bias: Seeking information that supports your beliefs.
Example: You strongly believe tech stocks will outperform, so you only read bullish articles and ignore reports warning of risks. - Mental Accounting: Treating money differently based on its source.
Example: You receive a $2,000 tax refund and splurge on a vacation because it feels like “extra” money, even though it’s part of your ordinary income. - Recency Bias: Assuming current trends will continue indefinitely.
Example: After a year of strong stock gains, you assume the rally will keep going and increase your equity exposure aggressively, forgetting that markets move in cycles.
Awareness of these behavioral biases is the first step toward making better financial decisions. Emotions can lead investors to react in ways that hurt long-term results, such as selling when markets fall and buying only after prices recover. Working with a financial advisor and having a disciplined plan helps you stay on track and avoid costly mistakes.
Bringing It All Together
Understanding these concepts helps you:
- Set realistic expectations: Markets will rise and fall, and that’s completely normal. Staying focused on the long term helps you avoid reacting to short-term noise.
- Diversify wisely: Don’t rely on one part of the market. Different assets perform better in different phases of the economic cycle, so a balanced mix can help reduce risk and smooth returns.
- Partner with your advisor: Investing isn’t just about numbers; it involves emotions too. A trusted advisor can help you stay disciplined, recognize cognitive traps, and keep your plan aligned with your goals and comfort level.
Wealthspire Advisors LLC and certain of its affiliates are separately registered investment advisers. © 2026 Wealthspire
This material should not be construed as a recommendation, offer to sell, or solicitation of an offer to buy a particular security or investment strategy. The information provided is for informational purposes only and should not be relied upon for accounting, legal, or tax advice. While the information is deemed reliable, Wealthspire cannot guarantee its accuracy, completeness, or suitability for any purpose, and makes no warranties with regard to the results to be obtained from its use.
Wealthspire and its representatives do not provide legal or tax advice, and Wealthspire does not act as law, accounting, or tax firm. Services provided by Wealthspire are not intended to replace any tax, legal or accounting advice from a tax/legal/accounting professional. The services of an appropriate professional should be sought regarding your individual situation. You should not act or refrain from acting based on this content alone without first seeking advice from your tax and/or legal advisors.
Certain employees of Wealthspire may be certified public accountants or licensed to practice law. However, these employees do not provide tax, legal, or accounting services to any of clients of Wealthspire, and clients should be mindful that no attorney/client relationship is established with any of Wealthspire's employees who are also licensed attorneys.
Please Note: Limitations. The achievement of any professional designation, certification, degree, or license, recognition by publications, media, or other organizations, membership in any professional organization, or any amount of prior experience or success, should not be construed by a client or prospective client as a guarantee that he/she will experience a certain level of results or satisfaction if Wealthspire is engaged, or continues to be engaged, to provide investment advisory services, nor should it be construed as a current or past endorsement of Wealthspire by any of its clients or a third party.
Registration of an investment advisor does not imply that Wealthspire or any of its principals or employees possess a particular level of skill or training in the investment advisory business or any other business.
Certified Financial Planner Board of Standards, Inc. (CFP Board) owns the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States, which it authorizes use of by individuals who successfully complete CFP Board's initial and ongoing certification requirements.