The Bull Market Turned Four. Now What?
Key Observations
- The Federal Reserve held its target rate at 3.75% to 4.00% in October as strong economic growth and elevated inflation kept policymakers cautious. Even so, Treasury yields retreated from September’s highs, easing pressure on markets.
- U.S. equity leadership shifted sharply. Greater scrutiny of AI-related capital spending weighed on many of the largest technology companies, while small-cap and value stocks moved higher, broadening participation beyond the market’s recent leaders.
- The decline in Treasury yields helped bonds rebound from September’s selloff. With weakness concentrated among large technology stocks, fixed income provided a meaningful source of diversification and helped offset some of the volatility in equities.
- Geopolitical tensions continued to reverberate through energy markets, keeping oil prices elevated and volatile.
Market Recap
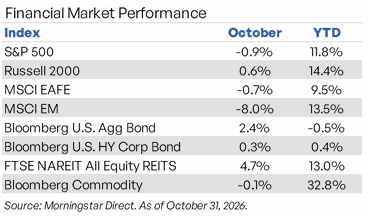
October marked a partial reversal of September’s market dynamics. Treasury yields declined as expectations for further Federal Reserve tightening eased, providing relief to bonds and other rate-sensitive assets. At the same time, concerns surrounding AI-related capital spending drove a sharp shift in equity market leadership.
U.S. equity returns were mixed but generally positive. The S&P 500 declined 0.9%, while the Russell 2000 gained 0.6% and the equal-weighted S&P 500 advanced 5.0%. Large technology companies came under pressure as investors placed greater scrutiny on the scale of AI investment and the prospective return on that spending, while small-cap, value, and defensive stocks benefited from the rotation.
International markets told two distinct stories. Developed markets declined 0.7%, while emerging markets fell 8.1%. Emerging markets fell sharply, with weakness concentrated in technology-heavy Asian markets following the reversal in AI-related stocks. Broader declines across several major emerging markets added to the index’s losses.
Fixed income rebounded following September’s selloff. The Bloomberg U.S. Aggregate Bond Index gained 2.4%, while high-yield bonds advanced 0.3%. Falling Treasury yields provided the strongest support to longer-duration securities, allowing core bonds to provide diversification as large-cap technology and emerging-market equities came under pressure.
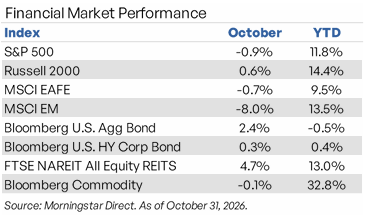
Real assets also benefited from the shift in interest rates. Listed real estate gained 4.7% as declining Treasury yields eased a key headwind, while commodities were essentially flat. Strength in energy offset weakness elsewhere as continued uncertainty surrounding Iran and Middle East supply routes kept oil prices elevated and volatile.
Celebrating Four Years of the Bull Market
Just over four years ago, the outlook for stocks felt anything but celebratory. Inflation remained stubbornly high, the Federal Reserve was raising interest rates at its fastest pace in decades, and fears of recession were building. By October 12, 2022, the S&P 500 Index had fallen approximately 25% from its January peak. What followed was a remarkable four-year advance, with the S&P 500 Index delivering a cumulative total return of approximately 130% through October 2026. Yet the market’s climb was far from smooth, giving investors plenty of reasons to question whether it could continue. Regional bank failures, persistent inflation, shifting interest-rate expectations, geopolitical tensions, and tariff uncertainty all interrupted the advance. Through every setback, however, the stock market recovered and the bull market charged on.
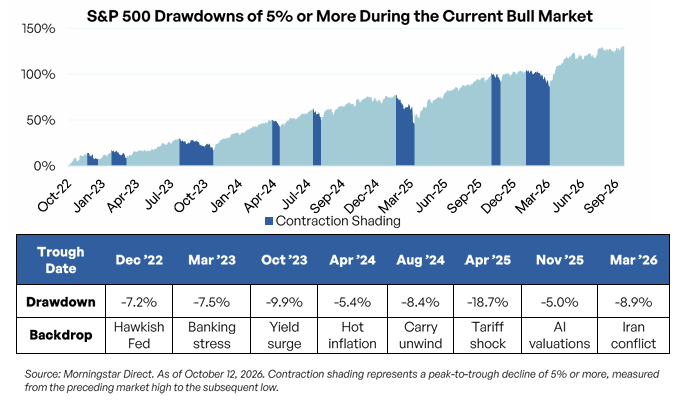
With four years of gains now in the rearview mirror, recency bias can make the market’s strength feel normal and a continued rise seem more likely. This anniversary offers an opportunity to look beyond the headline return and examine what has driven the advance, how it compares with past bull markets, and how several years of gains can shape investor behavior.
Bull Markets Don’t Run on a Timer
Since 1928, the median bull market has delivered a price gain of 78% over 633 calendar days. Through its four-year anniversary, the current advance has exceeded both measures. Does that mean the current advance has run its course? Not necessarily. Historical averages provide useful context, but they should not be treated as a countdown.
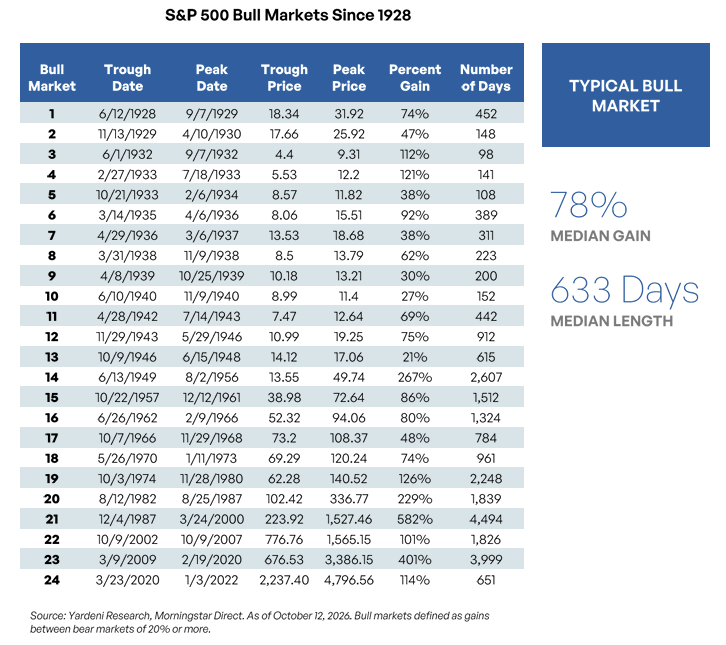
Bull markets have varied widely in length and magnitude, with some lasting only months and others continuing for more than a decade. That variation has also not been evenly distributed across history. Bull markets were generally shorter in the market’s earlier decades, particularly around the Great Depression and World War II, while those beginning after the 1950s have tended to last longer and, in several cases, deliver substantially larger gains.
The shift likely reflects a combination of forces. First, U.S. economic expansions have lasted an average of more than five years since World War II, roughly twice as long as those in the earliest part of the historical record, giving corporate earnings more time to grow and compound. Monetary policy also became a more active stabilizing force as the Federal Reserve gained greater independence and, in turn, was able to respond more effectively to periods of economic weakness. Technological advances also opened new avenues for productivity and profit growth. Later, from the mid-1980s through 2007, the Great Moderation brought greater stability to economic growth and inflation, creating a steadier backdrop for businesses and markets.
A bull market’s durability depends less on its age and more on the conditions supporting it. Economic growth, rising corporate earnings, and supportive financial conditions are all far more important factors than timing. Pressure emerges when the earnings outlook weakens, the price investors are willing to pay for those earnings declines, or both. The dot-com bubble was largely a story of valuation. By 2000, technology stock prices reflected growth expectations that many companies struggled to justify. Valuations also reset sharply in 2022, though for a different reason. Persistent inflation incited aggressive Federal Reserve rate hikes, raised borrowing costs, weakened the economic outlook, and reduced what investors were willing to pay for future earnings. Neither bull market ended because of its age. Both ended when the conditions supporting stock prices changed.
The Bull Market Enters Year Five
As the bull market enters its fifth year, the next phase will depend on the economic and earnings conditions beneath it. For now, both remain supportive. Real GDP expanded at a 3.4% annualized rate in the third quarter of 2026, accelerating from 2.2% in the second quarter.[1] Meanwhile, the S&P 500 is reporting blended earnings growth of approximately 30% for the third quarter, with 60% of companies having reported. If sustained, this would mark the third consecutive quarter of earnings growth above 25% and the eighth consecutive quarter of double-digit growth.[2]
However, strong fundamentals do not eliminate the risk of setbacks. Elevated market expectations leave less room for disappointment, particularly among companies whose valuations hinge on the continued pace of the AI buildout. The market also remains heavily influenced by a relatively small group of leading companies, magnifying the potential effect if their results fall short of expectations. Geopolitical tensions, renewed inflation, or an unexpected shift in economic conditions could further challenge the advance.
Hindsight is 20/20, and neither the market’s current strength nor the risks surrounding it can tell us when this bull market will end. Rather than trying to time the turning point, investors should focus on what they can control: their behavior and the composition of their portfolios.
When Fear of Loss Gives Way to Fear of Missing Out
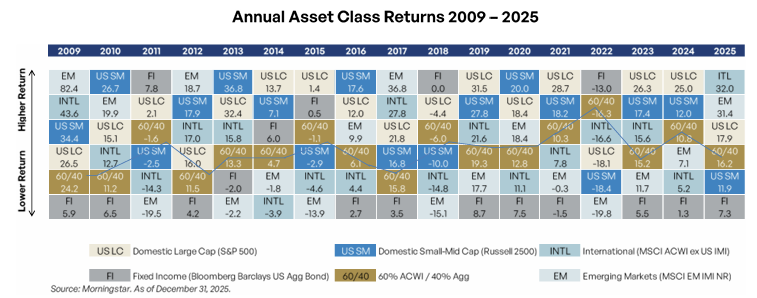
As gains accumulate in a bull market, fear of loss can give way to fear of missing out (FOMO), drawing investors toward the assets that have already performed best. Yet the return rankings below show how quickly leadership can change, even from one year to the next.
The bull market’s fourth anniversary offers an opportunity to step back and consider how portfolios have evolved over several years of equity market gains:
- Have strong returns pushed individual investments above their intended weights?
- Is the portfolio more dependent on a smaller group of companies or market segments than intended?
- Most importantly, does the portfolio still reflect its long-term objectives and intended level of risk?
Diversification can be difficult to appreciate when the market appears to have already identified the “winners.” Investors naturally want more exposure to what is working and less to what is not, but following recent leaders can leave a portfolio increasingly dependent on the conditions that fueled their success. The historical data offers a valuable reminder that no asset class remains on top indefinitely, and there is no reliable pattern for when leadership will change. Just as a bull market’s age cannot tell us when it will end, recent returns cannot tell us what will lead next. Markets rarely announce when leadership is about to shift. A strong bull market is an opportunity to step back, consider what has changed within a portfolio, and assess whether it remains properly aligned with its stated objectives.
Prefer to read this later?
Save a PDF version of the October Market Review - Beyond the Bull Run to reference or share with your team.
Disclosures & Definitions
This information is intended for the exclusive use of clients, prospective clients, and parties to whom it was provided by Wealthspire Advisors LLC, Wealthspire Institutional, LLC, and Wealthspire Retirement, LLC dba Wealthspire Retirement Advisory (collectively referred to as “Wealthspire”). The information contained herein is confidential and proprietary information of Wealthspire. Its contents may not be modified, disseminated, or distributed to any other person or entity without prior written approval of Wealthspire. Information has been obtained from sources believed to be reliable, though not independently verified and should not be regarded as a complete analysis of these subjects. The opinions and analysis expressed herein are based on Wealthspire’s research and professional experience and are expressed as of the date of this report and subject to change without notice. Any forecasts are hypothetical and represent future expectations and not actual returns. This does not contain investment advice. Please consult with your advisor, attorney, accountant, or other professionals, as appropriate, before making any investment, tax, or legal decisions. Past performance does not indicate future performance and there is risk of loss. This document is for informational and educational purposes only and is not an offer/recommendation to buy or sell any security, instrument, or strategy. Investment advisory services offered through Wealthspire Advisors LLC, Wealthspire Institutional, LLC, or Wealthspire Retirement, LLC, each separately registered investment advisers.
Comparisons to any indices referenced herein are for illustrative purposes only and are not meant to imply that actual returns or volatility will be similar to the indices. Indices cannot be invested in directly. Unmanaged index returns assume reinvestment of any and all distributions and do not reflect our fees or expenses. Market returns shown in text are as of the publish date and source from Morningstar or FactSet unless otherwise listed.
The S&P 500 is a capitalization-weighted index designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries.
S&P 500 Equal Weighted Index measures the performance of 500 leading publicly traded U.S. companies from a broad range of industries. It has the same constituents as the market-capitalization weighted S&P 500, but each company is allocated the same weight – 0.2%.
Russell 2500 Index measures the performance of the small- to mid-cap segment of the US equity universe. It is a subset of the Russell 3000 Index that includes approximately 2500 of the smallest securities based on a combination of their market cap and current index membership. It is a market-capitalization weighted index.
Russell 2000 consists of the 2,000 smallest U.S. companies in the Russell 3000 index.
Russell 2000 Growth measures the performance of the Russell 2000 companies with higher P/B ratios and higher forecasted growth values.
MSCI EAFE is an equity index which captures large and mid-cap representation across Developed Markets countries around the world, excluding the U.S. and Canada. The index covers approximately 85% of the free float-adjusted market capitalization in each country.
MSCI Emerging Markets captures large and mid-cap representation across Emerging Markets countries. The index covers approximately 85% of the free-float adjusted market capitalization in each country.
MSCI ACWI ex-USA Investable Market Index (IMI) measures the performance of large-, mid-, and small-cap companies across 22 of 23 developed markets countries, excluding the United States, and 24 emerging markets countries. It is a market-capitalization weighted index.
Bloomberg U.S. Aggregate Index covers the U.S. investment grade fixed rate bond market, with index components for government and corporate securities, mortgage pass-through securities, and asset-backed securities.
Bloomberg U.S. Corporate High Yield Index covers the universe of fixed rate, non-investment grade debt. Eurobonds and debt issues from countries designated as emerging markets (sovereign rating of Baa1/BBB+/BBB+ and below using the middle of Moody’s, S&P, and Fitch) are excluded, but Canadian and global bonds (SEC registered) of issuers in non-EMG countries are included.
FTSE NAREIT Equity REITs Index contains all Equity REITs not designed as Timber REITs or Infrastructure REITs.
Bloomberg Commodity Index is calculated on an excess return basis and reflects commodity futures price movements. The index rebalances annually weighted 2/3 by trading volume and 1/3 by world production and weight-caps are applied at the commodity, sector and group level for diversification.
Material Risks
Fixed Income securities are subject to interest rate risks, the risk of default and liquidity risk. U.S. investors exposed to non-U.S. fixed income may also be subject to currency risk and fluctuations.
Cash may be subject to the loss of principal and over longer periods of time may lose purchasing power due to inflation.
Domestic Equity can be volatile. The rise or fall in prices take place for a number of reasons including, but not limited to changes to underlying company conditions, sector or industry factors, or other macro events. These may happen quickly and unpredictably.
International Equity can be volatile. The rise or fall in prices take place for a number of reasons including, but not limited to changes to underlying company conditions, sector or industry impacts, or other macro events. These may happen quickly and unpredictably. International equity allocations may also be impacted by currency and/or country specific risks which may result in lower liquidity in some markets.
Real Assets can be volatile and may include asset segments that may have greater volatility than investment in traditional equity securities. Such volatility could be influenced by a myriad of factors including, but not limited to overall market volatility, changes in interest rates, political and regulatory developments, or other exogenous events like weather or natural disaster.
Private Real Estate involves higher risk and is suitable only for sophisticated investors. Real estate assets can be volatile and may include unique risks to the asset class like leverage and/or industry, sector or geographical concentration. Declines in real estate value may take place for a number of reasons including, but are not limited to economic conditions, change in condition of the underlying property or defaults by the borrower.
All investing involves risk including the potential loss of principal. Market volatility may significantly impact the value of your investments. Recent tariff announcements may add to this volatility, creating additional economic uncertainty and potentially affecting the value of certain investments. Tariffs can impact various sectors differently, leading to changes in market dynamics and investment performance. You should consider these factors when making investment decisions. We recommend consulting with a qualified financial adviser to understand how these risks may affect your portfolio and to develop a strategy that aligns with your financial goals and risk tolerance.
[1] U.S. Bureau of Economic Analysis. As of 10/29/2026.
[2] FactSet Earnings Insight. As of 10/30/2026.